
KYC Requirements in France
Navigate French KYC and LCB-FT requirements while protecting customers from evolving identity fraud. France's digital identity landscape is evolving under the revised eIDAS 2.0 framework, which introduces the European Digital Identity Wallet (EUDI Wallet), and AMLR.
Entrust brings together identity verification, fraud detection, qualified electronic signatures (QES) and workflow orchestration to help organizations build secure, adaptable and customer-friendly journeys. With Entrust, you can prepare for a future where trusted digital identity credentials can be reused across the EU for onboarding, authentication, and signing workflows.


Solution Highlights

Prepare for the Future of Digital Identity in Europe
Navigate French KYC requirements today while preparing for tomorrow's interoperable digital identity ecosystem. Entrust's identity proofing is certified against ETSI standards to support what's coming: eIDAS 2.0, the EU Digital Identity Wallet, and EU-wide AML reform.
Build Trust Without Increasing Friction
By combining document verification, biometrics, fraud detection, Qualified Electronic Signatures (QES), and authentication, organizations can strengthen identity assurance, combat sophisticated fraud, and deliver faster customer experiences across the lifecycle.
Simplify Compliance and Digital Onboarding
Bringing customer verification, risk-based due diligence, remote onboarding and signing into a single, off-the-shelf workflow template to reduce complexity, improve operational efficiency, and meet evolving regulatory requirements from day one.
How Can Entrust Help?
Support KYC / AML compliance or Navigate KYC requirements
Build digital customer journeys designed for French KYC and LCB-FT compliance. Start from templates built around French KYC practice rather than a blank canvas, so you can configure onboarding flows that support your regulatory obligations faster.

Reduce complexity
Bring identity verification, fraud signals, and qualified electronic signatures into one connected workflow. Entrust offers global document coverage including multiple French document types including passport, National Identity card, National Health Insurance card, and more.
Accelerate customer onboarding
Create fast, intuitive onboarding journeys that help legitimate customers prove who they are quickly. Our SDK also supports translations for 44 languages implemented directly inside the application, including French.

Prevent sophisticated fraud
Stay ahead of evolving, sophisticated fraud threats such as deepfakes, injection attacks and organized fraud rings, while preserving the fast, low‑friction onboarding genuine users expect.

Build trust in high-value transactions
Combine identity verification, fraud detection, and qualified electronic signatures to establish greater confidence in onboarding, account creation, agreement signing, and other high-assurance digital interactions.
Apply the right level of assurance
Tailor onboarding requirements based on customer risk, geography, fraud signals, and business policies. Plus, automate decisioning while maintaining the flexibility to adapt as regulations and threats evolve in Workflow Studio.

"Onfido's (now part of Entrust) Compliance Suite helps us to meet local compliance regulations in all the countries we are expanding in while maintaining a consistently high-quality user experience that our customers have come to expect. With Entrust, we are now able to build a high-performing, secure, and convenient onboarding experience that will unlock our ability to scale across multiple geographies quickly."

"We are never going to compromise when it comes to the user experience which we are offering to our clients and their communities of users. This new partnership allows us to further improve our KYC experience in an evolving regulatory framework."

"Onfido (now part of Entrust) has really aligned with our priorities, working with us to achieve our desired delivery by rapidly responding and iterating on their offering. Direct contact between our engineering teams has fostered a mutually beneficial partnership – identifying problems early, collaborating on solutions and improving the overall integration."
What Are the KYC Requirements in France?
For remote onboarding, French organizations frequently rely on ANSSI-certified PVID (Prestataire de Vérification d'Identité à Distance) services to support their KYC and LCB-FT obligations, and French supervisory expectations emphasize robust customer identification, verification, and risk-based due diligence.
But the picture is shifting. France's PVID scheme is a national framework, while the EU is converging towards harmonized requirements for remote identity proofing under eIDAS 2.0, built for cross-border interoperability and designed to underpin the European Digital Identity (EUDI) Wallet. From July 2027, the EU Anti-Money Laundering Regulation (AMLR) will also directly harmonize core customer due diligence requirements across member states.
For French organizations, the goal is no longer just meeting today's national expectations, it's choosing an approach that works within France’s PVID-influenced standards and scales into the EU-wide framework arriving in 2027.


How Will France Identité and eIDAS 2.0 Impact Digital Identity Verification?
France has positioned France Identité to serve as France's EUDI Wallet, aligning the national digital identity app with eIDAS 2.0 and the EU-wide framework for cross-border identity. These developments are designed to enable individuals to securely reuse trusted digital identity credentials across EU member states, making it easier to access services, complete transactions, and prove identity online.
For organizations, this shift has the potential to transform digital onboarding, customer verification, and authentication. Reusable, high-assurance digital identities can help reduce customer friction, streamline onboarding journeys, and create more seamless cross-border experiences while maintaining strong identity assurance.
This timeline is regulatory driven and not optional. Member states must make EUDI Wallets available by the end of 2026, and from the end of 2027 many organizations, including in KYC contexts, will be required to accept them. As adoption grows, financial institutions and other regulated organizations should begin preparing for wallet-based identity verification as part of their long-term digital onboarding strategies.
How can QES support remote customer onboarding in France?
A Qualified Electronic Signature provides the highest level of electronic signature assurance under eIDAS. In a remote onboarding journey, QES can do more than support document signing. French law expressly recognizes the collection of a qualified electronic signature as one of the identity verification measures available to obliged entities under the Code monétaire et financier, when combined with other required measures. And because issuing a qualified certificate requires identity verification at a high level of assurance, pairing QES with strong identity verification helps establish a trusted link between the person, the verified identity and the signing event.
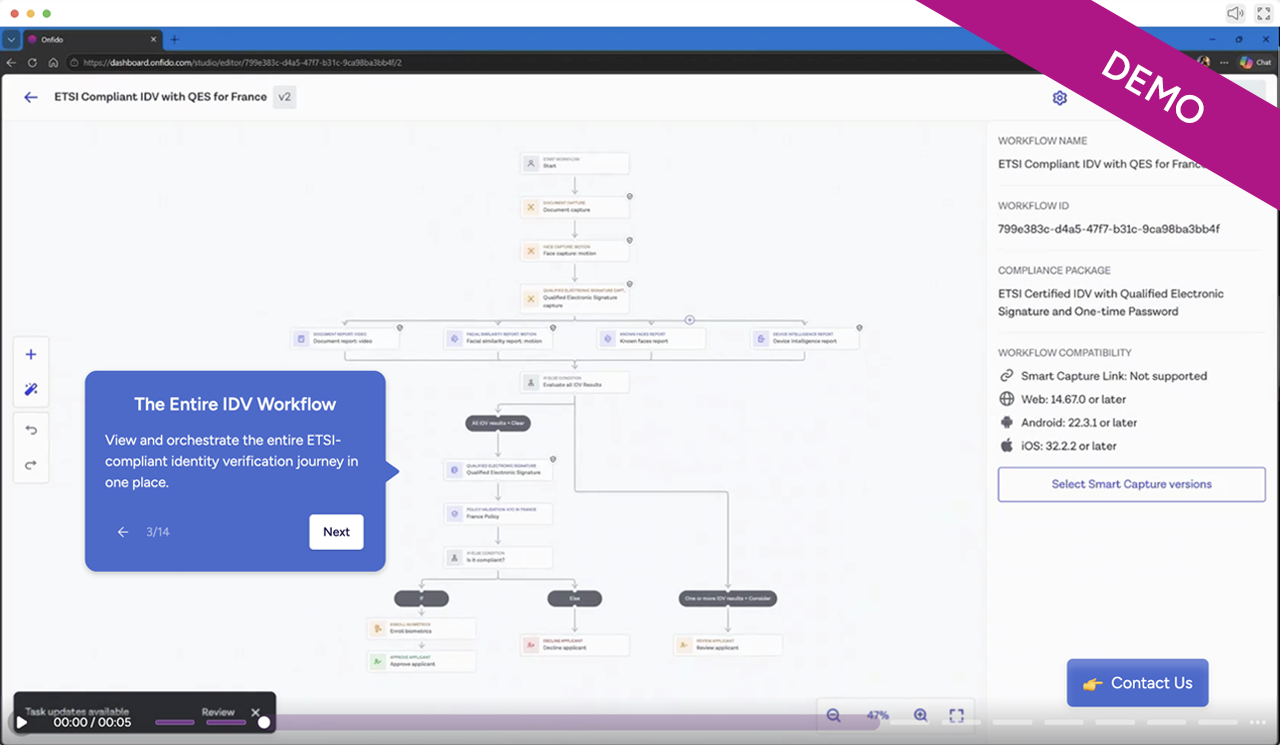
Entrust combines identity verification and QES within a connected Workflow Studio journey, enabling organizations to coordinate document and biometric verification, fraud signals, policy decisions, signing and evidence generation without creating a disconnected customer experience.


How Does Entrust Help?
Organizations need a flexible approach to digital onboarding that can adapt as regulations, fraud threats, and customer expectations continue to evolve. Entrust helps organizations build trusted digital onboarding journeys by bringing together identity verification, fraud detection, Qualified Electronic Signatures (QES), and workflow orchestration in a single platform. With Entrust, you can verify identities, apply risk-based controls, collect supporting evidence, and enable secure signing experiences while maintaining a seamless customer journey.
Our Identity Verification solutions are ETSI-certified and support high-assurance identity proofing aligned with evolving European standards. Combined with QES, Entrust helps organizations strengthen fraud prevention, support digital trust initiatives, and create onboarding experiences that are secure, compliant, and customer-friendly.
With Entrust, French organizations can address today's KYC requirements while preparing for a future where trusted digital identities can be reused across onboarding, authentication, and signing workflows throughout Europe.


Identity Verification Solutions for KYC in France

Entrust Identity Verification Compliance
Entrust’s IDV solution is an eIDAS-compliant onboarding solution for regulated industries, such as financial services. ETSI-certified identity verification (comprising Document Verification, Biometric Verification, and Device Intelligence) and QES are brought together in Workflow Studio, creating a flexible, user-friendly, and compliant end-to-end workflow.


Deploy ETSI-Compliant Identity Verification with QES in France
Entrust’s Workflow Studio can help you orchestrate identity verification, prevent fraud, and implement qualified electronic signatures for customers in France. Explore our demo to see how it works behind the scenes.
Compliance Certifications
We help hundreds of businesses navigate compliance worldwide. Our solution meets ETSI TS 119 461, ETSI EN 319 401, eIDAS Regulation EU 2014/910, and the UK’s Digital Identity and Attributes Trust Framework.

ETSI TS 119 461 in 2025 to support newer identity-proofing requirements


The Identity Shift: Preparing for Europe's New Regulatory Era
Learn what the latest eIDAS 2.0, ETSI v2, EUDI Wallet, and Anti-Money Laundering Regulation (AMLR) changes mean for financial institutions, and how to build a fraud-resistant compliance strategy before the 2027 deadlines arrive.
FAQs
What are the KYC requirements in France?
French KYC requirements generally require organizations to identify and verify customers, understand beneficial ownership structures, assess customer risk, and apply ongoing due diligence measures. Regulated organizations must also comply with France's anti-money laundering and counter-terrorist financing (LCB-FT) obligations, which are overseen by authorities including the ACPR and AMF. This increasingly includes the use of secure remote identity verification for digital onboarding.
Can customer onboarding be completed remotely in France?
Yes. Many organizations use remote identity verification to onboard customers without requiring an in-person visit. France's regulatory framework supports remote onboarding approaches that provide appropriate levels of identity assurance, and organizations often leverage document verification, biometric verification, and fraud detection technologies to establish trust during the onboarding process.
What is the European Digital Identity (EUDI) Wallet and why does it matter in France?
The EUDI Wallet is part of the European Union's eIDAS 2.0 framework and is intended to allow individuals to securely reuse trusted digital identity credentials across Europe. As adoption grows, organizations may be able to streamline onboarding and authentication processes while reducing customer friction and supporting cross-border digital services. French organizations should consider how evolving digital identity standards may impact future customer onboarding journeys.
How can French organizations prevent identity fraud during remote onboarding?
France's growing adoption of digital onboarding increases the need to defend against document fraud, account takeover attempts, synthetic identities, injection attacks, and AI-generated deepfakes. Organizations increasingly combine document verification, biometric verification, fraud detection, and risk signals to establish trust while maintaining a positive customer experience.
Talk to Entrust about automated identity verification workflows that help meet French and EU compliance requirements while reducing fraud and onboarding friction.
Legislative and regulatory requirements can vary by jurisdiction, industry, product, and use case and may change over time. The information provided on this page is for general informational purposes only and reflects our understanding as of the date of publication. It does not constitute, and should not be relied upon as, legal, regulatory, or compliance advice. You should consult your own legal, compliance, or regulatory advisors regarding any questions or requirements that may apply to your business.